

The Signal
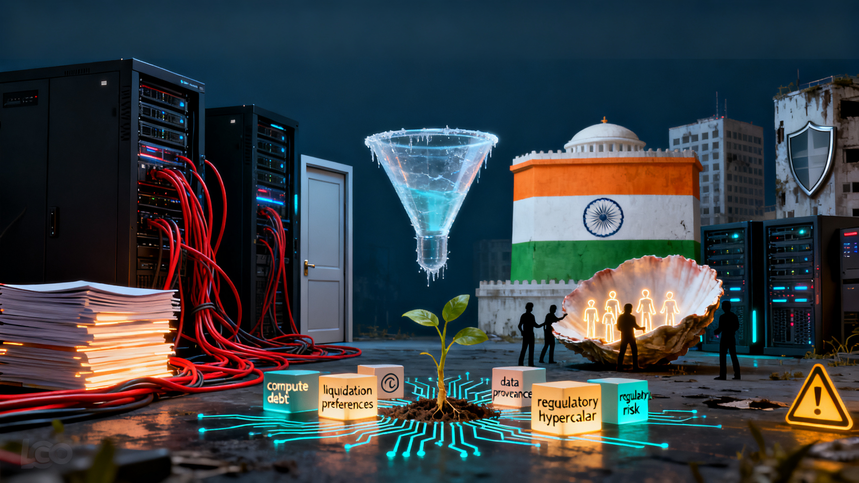
The exit market for early-stage artificial intelligence companies has effectively frozen. Despite global AI funding reaching $202.3 billion in 2025, capital velocity has decoupled from acquisition logic. The ecosystem has entered a “Zombie Phase”—a structural deadlock where seed-stage valuations structurally prohibit standard M&A exits. The data is unyielding: only 15.4% of startups that raised seed rounds in 2022 successfully reached Series A by 2024-2025.
- The Signal
- The Structural Shift: “Reverse Acqui-hires” and Compute Debt
- The Contrarian Thesis: The Reverse Due Diligence Trap
- First-Principles Analysis: Inference vs. Liquidation Preference
- Signal vs Noise: The Execution Gap
- Ground Truth: The India Compute Moat
- Founder Considerations for 2026
- The Sovereign Playbook
What we are witnessing is not a cyclical downturn, but a recalibration of how incumbent technology platforms assess asset value. Big Tech no longer acquires companies; they harvest them, isolating human talent from the corporate shell to bypass regulatory friction and toxic technical debt. For the 2026 founder, understanding the physics of this transition is the prerequisite for avoiding systemic insolvency.
The Structural Shift: “Reverse Acqui-hires” and Compute Debt
The expansion of the Seed-to-Series A deal ratio to a 2:1 disparity has triggered a Barbell Funding dynamic. Capital is heavily concentrated at the infrastructure layer or at hyper-scalable application endpoints, starving the middle class of AI software.
Incumbents have pioneered the “Reverse Acqui-hire” to extract intelligence without inheriting corporate liability. Microsoft established the blueprint by paying $650 million for a non-exclusive license and hiring 80% of the team from Inflection AI. Amazon rapidly replicated this architecture, hiring 66% of the staff alongside a $25 million licensing fee for Adept AI. These maneuvers leave behind hollowed-out legal entities, bypassing traditional antitrust oversight.
The underlying structural deterrent is Off-Balance-Sheet Compute Debt. The hyper-scalers (Alphabet, Amazon, Microsoft, Meta, Oracle) sit on $1.65 trillion in off-balance-sheet AI obligations. They have zero appetite to acquire a startup carrying its own long-term, high-interest compute liabilities, especially when AI startup unit economics at the seed stage rarely justify the processing costs required to maintain competitive foundational performance.
The Contrarian Thesis: The Reverse Due Diligence Trap
The consensus narrative assumes startups fail to exit due to poor product-market fit or an inability to capture revenue. The 2026 reality is vastly different: M&A transactions are failing during Technical Due Diligence (TDD) because the underlying models are classified as legal toxic waste.
Acquirers now prioritize “Data Provenance Audits.” If a seed-stage model is caught in “Model Memorization Risk”—where it regurgitates Personally Identifiable Information (PII) from unauthorized scraping—the acquirer faces a systemic threat. Under GDPR and the strict transparency mandates of the EU AI Act’s rules for General Purpose AI, a non-compliant model is a “Kill Switch.” Regulatory agencies can enforce the “Right to Erasure,” legally compelling the deletion of the entire model weight architecture.
The financial consequences of IP Contamination are profound. Following the $1.5 billion Anthropic copyright settlement in 2025, no enterprise compliance officer will sign off on an acquisition lacking a rigorous compute governance framework. Yet, the supply side is wholly unprepared: while 78% of organizations use AI, only 14% have enterprise-level AI governance frameworks.
First-Principles Analysis: Inference vs. Liquidation Preference
The economic mechanics preventing seed-stage acquisitions come down to the divergence between Inference Unit Economics and Liquidation Preference Overhang.
1. Marginal Cost of Intelligence (MCI): As open-source models rapidly push the marginal cost of generic intelligence toward zero, the valuation moat of “wrapper” applications collapses. Without proprietary data architecture, LTV/CAC ratios decouple—customer acquisition costs remain high, while the lifetime value drops due to near-infinite market substitution.
2. Liquidation Preference Overhang: Companies that raised $10M at $50M post-money valuations in 2022–2023 now face a mathematical trap. To generate a 3x return for seed investors, an acquisition must clear $150M. But an acquirer evaluating a startup with negative operating leverage (where compute scaling outpaces revenue generation) values the underlying technology at a fraction of that cost. The resulting gap creates an un-acquirable zombie.
3. The Preference Stack Math: Founders are left holding common stock heavily subordinated beneath layers of preferred equity. In an asset-light acqui-hire scenario, investors weaponize their liquidation preferences to block the transaction entirely, freezing the founder in a structurally unviable company.
Signal vs Noise: The Execution Gap
| The Narrative (Noise) | The Execution Reality (Signal) | Structural Implication |
|---|---|---|
| “We have proprietary models trained on unique industry data.” | Models suffer from IP Contamination and lack rigorous data provenance trails. | Triggers the Reverse Due Diligence Trap; startup is classified as a toxic asset by Enterprise compliance. |
| “We are optimizing inference to achieve positive unit economics.” | Compute debt compounds faster than MRR growth; Negative Operating Leverage. | Incumbents refuse to absorb expensive cloud contracts, preferring to harvest the engineering team instead. |
| “Our valuation positions us perfectly for a strategic acquisition by Big Tech.” | Liquidation Preference Overhang blocks any realistic asset sale. | Seed investors veto low-valuation exits, stranding the founders in a zombie operational state. |
Ground Truth: The India Compute Moat
The global governance vacuum provides a distinct asymmetric advantage for the Indian AI ecosystem. Western startups are increasingly paralyzed by the collision of aggressive data scraping and the EU AI Act. Conversely, Indian founders operating under strict MeitY liability mandates are inadvertently building structurally acquirable assets.
By prioritizing “Clean Data Bastions”—verifiable, localized datasets that strictly adhere to sovereign compliance structures—Indian startups bypass IP Contamination. They are effectively substituting massive raw compute for high-fidelity data provenance. Furthermore, the Indian structural bias toward capital efficiency forces founders to solve Inference Unit Economics immediately, rendering them highly attractive to US and EU acquirers desperate for compliant, low-burn AI integration. The local moat in 2026 is no longer just engineering talent; it is regulatory arbitrage through pre-audited algorithmic transparency.
Founder Considerations for 2026
To avoid the zombie consolidation trap, founders must ruthlessly optimize for Technical Acquirability over top-line vanity metrics.
- Technical Due Diligence (TDD) Readiness: Implement cryptographic data provenance from day one. If you cannot mathematically prove where a specific model weight derived its influence, your company is heavily discounted by institutional M&A teams.
- Navigating Acquihire Thresholds: Founders must actively model their Preference Stack Math. If the required exit velocity exceeds the buyer’s willingness to pay for a team’s Marginal Cost of Intelligence, initiate capitalization restructuring. Down rounds that reset the liquidation preference stack are vastly superior to a zombie deadlock.
- Isolating IP from Compute Liabilities: Structure vendor agreements strictly to avoid locking the corporate entity into multi-year inference contracts. Acquirers want to port your weights into their proprietary infrastructure, not inherit your negotiated cloud debt.
The Sovereign Playbook
The ultimate defense against the hollowing out of AI startups requires adopting a sovereign stance on capital allocation and architectural control. The most resilient entities in 2026 do not view themselves as candidates for Big Tech absorption; they design their infrastructure for multi-decade leverage.
Building sovereign advantage requires decoupling from consensus cloud architecture. It necessitates investing in proprietary, edge-deployable smaller models (SLMs) where local data loops compound value without transmitting intelligence back to foundational model providers. Founders executing this playbook allocate capital toward deep workflow integration and verifiable data moats, recognizing that true long-term defensibility relies on making switching costs impossibly high for the end enterprise.
In this landscape, asymmetric payoffs belong to those who build unshakeable compliance and economic viability into their base layers. When the broader market is consumed by the friction of toxic assets and unpayable compute debts, structural authority is the only currency that commands a premium.